Cargo Insurance Explained: What It Covers & What It Doesn't
- Carrier liability is capped at roughly $3 per kg under maritime conventions — insurance is the only real protection.
- All-risk cover (Institute Cargo Clauses A) costs about 0.15–0.4% of insured value.
- Clauses B and C cover only listed perils; most everyday losses (theft, handling damage, water) are excluded.
- Standard exclusions: bad packing, inherent vice, delay, ordinary leakage, pre-shipment damage.
- Insure for CIF value + 10%, and photograph cargo condition before it leaves the factory.
Cargo insurance is a policy that pays you for physical loss of or damage to your goods during transit — sinking, fire, theft, rough handling, water ingress — regardless of who caused it. It is the only protection that compensates full commercial value, because carrier liability is capped at roughly 2 SDR per kg (about $3), which covers a fraction of what most containers are actually worth.
Every year importers discover this the hard way. A container of furniture shifts in heavy weather; a pallet disappears between two terminals; a caught-up LCL parcel arrives soaked. The freight was never "free of risk" — it was simply uninsured, and the recovery conversation with the carrier ends very quickly at the liability cap. This guide explains what policies actually cover, what they don't, what cover should cost, and how a claim works when you need one.
Isn't My Cargo Already Covered by the Carrier or Forwarder?
No — and this is the single most expensive misunderstanding in international trade. Ocean carriers operate under liability limits set by international maritime conventions: approximately 666.7 SDR per package or 2 SDR per kilogram, whichever is higher (an SDR — Special Drawing Right — is an IMF currency basket currently worth around $1.35). Air carriers have a higher limit under the Montreal Convention, but still not full value.
Run the math on a real scenario: a 40HC container with $60,000 of home appliances is lost overboard in a storm. At 2 SDR/kg with 18,000 kg of cargo, the theoretical maximum carrier liability is about $48,600 — but only if the carrier accepts liability at all, which it often won't for causes it classifies as navigational or outside its control. In practice, without insurance, recovery on a total loss frequently lands between a few hundred and a few thousand dollars. Claims specialists such as TT Club, which insures the transport industry itself, spend much of their time on exactly this gap between cargo value and carrier liability.
Cargo insurance closes that gap completely: the policy responds for the full insured value regardless of fault.
One peril deserves special mention because it surprises importers more than any other: general average. When a ship's master deliberately sacrifices cargo to save the voyage — containers jettisoned in a storm, a fire flooding the hold — all cargo owners share the loss proportionally, including those whose cargo was saved undamaged. A general average declaration can freeze cargo at destination until the owner posts a security deposit, often a five-figure sum on a full container. All-risk cargo insurance absorbs the contribution and, crucially, the insurer posts the security so your goods keep moving. This single clause justifies the premium for many high-value shipments.
When Should You Buy the Insurance — and from Whom?
Follow the Incoterm. Under CIF or CIP terms, your supplier is contractually obliged to insure the cargo — but often at the minimum legal level (Clauses C for CIF under Incoterms 2020) and for their convenience, not yours. Check the certificate they issue; it frequently names them as loss payee and covers only the main carriage, not the destination leg.
Under FOB, EXW or FCA — the terms most wholesale buyers actually use — insurance is your responsibility, and you have two ways to buy it: through your freight forwarder per shipment, or through your own annual open policy if you ship frequently. Forwarder-arranged cover suits most small and mid-size importers: one premium per shipment, no minimums, the forwarder files the claim with you. An open policy suits importers shipping weekly — better rates, but you must declare each shipment accurately and on time, or cover lapses.
Either way, buy the cover before the cargo leaves the factory. Warehouse-to-warehouse cover that starts at pickup is what protects the legs most importers forget: the truck to the port and the container yard.
What Are the Levels of Cargo Insurance Cover?
International cargo insurance is built on the Institute Cargo Clauses, published through the London insurance market (Lloyd's being the best-known). The three standard levels are:
| Clause | Nickname | What it covers | What it misses (examples) | Typical premium | Best for |
|---|---|---|---|---|---|
| Institute Cargo Clauses (A) | All risks | All loss or damage from external causes — theft, handling damage, water, fire, sinking, collision | Exclusions only: bad packing, inherent vice, delay, war/strikes unless endorsed | 0.15–0.4% of value | Almost all commercial cargo |
| Institute Cargo Clauses (B) | Named perils (medium) | Fire, explosion, grounding, collision, water entry, jettison, washing overboard | Theft (except with violence), handling damage, sweat/contamination | ~0.1–0.25% | Bulk commodities, rugged cargo |
| Institute Cargo Clauses (C) | Named perils (minimum) | Fire, explosion, vessel grounding/stranding, collision, general average sacrifice | Nearly everything else — water damage, theft, breakage | ~0.05–0.15% | Very low-value, highly rugged cargo only |
For containerized general cargo from China, Clause (A) is the only form we recommend. The perils that actually destroy containers — water ingress, rough handling, pilferage — are precisely the ones (B) and (C) leave out. A client once asked us to save $140 on the premium by using Clauses (C); three months later a ventilation-soaked carton stack wrote off $4,200 of stock that an all-risk policy would have paid in full.
What Does Cargo Insurance NOT Cover?
Even all-risk Clause (A) has exclusions, and most declined claims die on one of these:
- Insufficient or unsuitable packing. Goods packed for a showroom, not for a 30-day ocean voyage, are the number-one claim killer. Insurers expect export-grade cartons, palletization and moisture protection.
- Inherent vice and ordinary leakage. Goods that spoil, rust, shrink or evaporate by their own nature are not insurable losses under standard terms.
- Delay. Even if a covered peril delays your goods and you lose a selling season, standard policies pay for the goods, not the lost market.
- Pre-shipment damage. If the cartons were already crushed before the transit began, that's a supplier dispute, not an insurance claim — another reason warehouse photos at pickup matter.
- War, strikes, cyber events — unless you buy specific endorsements.
- Unseaworthiness you knew about, and losses caused deliberately by the insured.
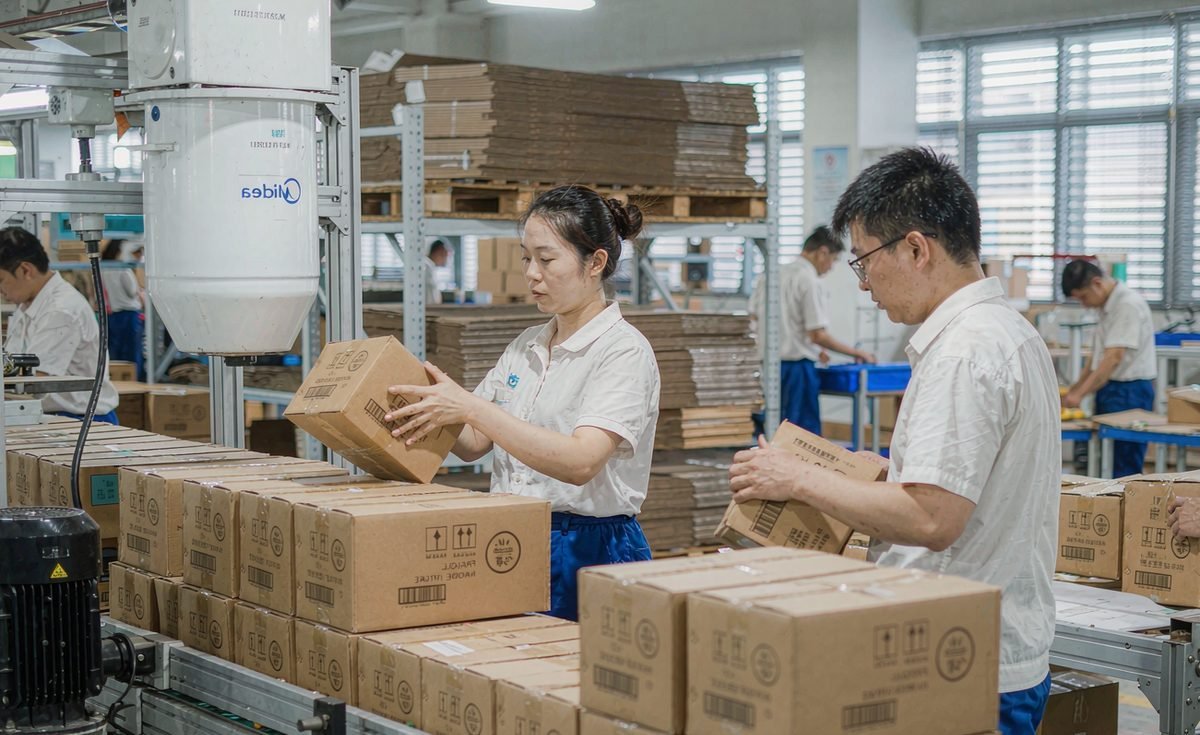
Notice what sits at the top of that list: packing. It is also the exclusion that is entirely within your control. When our Shenzhen warehouse receives cargo for palletizing, the crew rejects cartons that are double-stacked beyond their crush rating, wrapped in loose retail film, or missing internal bracing — not to be difficult, but because an insurer will pay nothing on a crushed pallet that was packed that way at origin. Spend the extra $2 per carton on export-grade boxes and proper void fill; it is the cheapest premium reduction available in this whole article.

How Much Does Cargo Insurance Cost — and How Do You Value the Cargo?
Premiums for general cargo typically run 0.15–0.4% of insured value, with the higher end applying to fragile, used, or high-theft cargo and some destinations. Insured value should be your CIF value plus 10% — invoice value plus freight, with a 10% cushion for your costs and a slice of margin. On a $50,000 CIF shipment, expect roughly $90–$260 for full-transit, warehouse-to-warehouse all-risk cover. For context on why premiums track risk, market analyses from Xeneta and claims data from insurers consistently show loss rates spiking in congestion periods and on transshipment-heavy routings.
Tips that keep claims clean and premiums fair:
- Declare accurate values — under-insuring triggers average, where the insurer pays only a proportional share of any loss.
- Cover every leg, including the truck to port and the warehouse delivery at destination; good policies are door-to-door.
- Photograph goods and packing at the factory and at warehouse receipt. Timestamped photos win disputes.
- If your routing involves multiple transshipments, say so — a direct vs transshipment decision changes both risk and premium.
How Do You Claim on Cargo Insurance?
- Notify immediately. Policies require prompt notice — often within 3–14 days of discovery. Call your forwarder the day you find damage.
- Preserve everything. Keep damaged goods, packaging and seals exactly as found; the surveyor must see them. Signing a clean POD for visibly damaged cargo is the classic self-inflicted wound.
- Request a survey. For anything significant, the insurer appoints a surveyor at destination; their report anchors the claim.
- Assemble the file. Commercial invoice, packing list, bill of lading or air waybill, photos, survey report, correspondence with the carrier.
- Settlement. With complete documentation, straightforward claims settle in roughly 30–90 days. Incomplete files are what stretch to a year.
Our claims team pre-checks documents before departure so the file is claim-ready from day one — and we handle the insurer liaison so you don't navigate policy language alone. If fees and liability ever feel muddled in your quotes, our hidden fees explainer and our customs documents guide both show which paperwork protects you and which doesn't.
Frequently Asked Questions
What does cargo insurance cover on a shipment from China?
Under the broadest form, Institute Cargo Clauses (A), cargo insurance covers physical loss or damage from external causes — sinking, fire, collision, theft, rough handling, water damage — from warehouse to warehouse for the insured transit. Narrower forms (Clauses B and C) cover only listed perils such as fire, grounding or collision, leaving many common losses unpaid.
Isn't my cargo already covered by the shipping line?
No. Carrier liability under international maritime conventions is limited to roughly 2 SDR per kilogram (about $3) or 666.7 SDR per package — whichever is higher — and carriers escape liability entirely for many causes. A $40,000 container of goods lost overboard could recover only a few hundred dollars without cargo insurance.
How much does cargo insurance cost from China?
For most general cargo, all-risk marine insurance costs between 0.15% and 0.4% of the insured value, which is typically invoice value plus freight plus 10%. On a $50,000 CIF shipment that is roughly $90–$260 per shipment. Higher rates apply to used goods, fragile cargo and certain high-theft or high-risk destinations.
What is NOT covered by cargo insurance?
Standard exclusions include ordinary leakage and wear, inherent vice (goods spoiling by their own nature), insufficient or unsuitable packing, delay even when caused by a covered peril, insolvency of the carrier, war and strikes on unendorsed policies, and pre-shipment damage that occurred before the insured transit began.
How do I claim on cargo insurance?
Notify the insurer or your forwarder immediately on discovery — many policies require notice within days — then preserve the damaged goods and packaging for survey. Gather the commercial invoice, packing list, bill of lading or air waybill, the survey report and photos. Complete claims are typically settled within 30–90 days of full documentation.
- Golden Week Dispatch Guide: What Closes & What Doesn't
- How to Load Textiles & Apparel into a Container Without Damage
- Shipping Steel & Metal Products from China: The Complete Exporter's Guide
- How to Load Ceramics & Tableware into a Container Without Damage
- Shipping from Guangzhou to Hamburg: Rates, Transit Times & Booking Guide
- Shipping from China to Japan: The Complete 2027 Guide
Get Today's Rate & Lock Your Discount
Waymore Shipping offers FCL & LCL ocean freight from every major port in China — Shanghai, Ningbo, Shenzhen, Guangzhou, Qingdao, Xiamen, Tianjin and more. Rates updated weekly with carrier discounts.